The First Iraqi Bank (FIB) App: Does It Truly Reflect the Future of Digital Banking in Iraq?
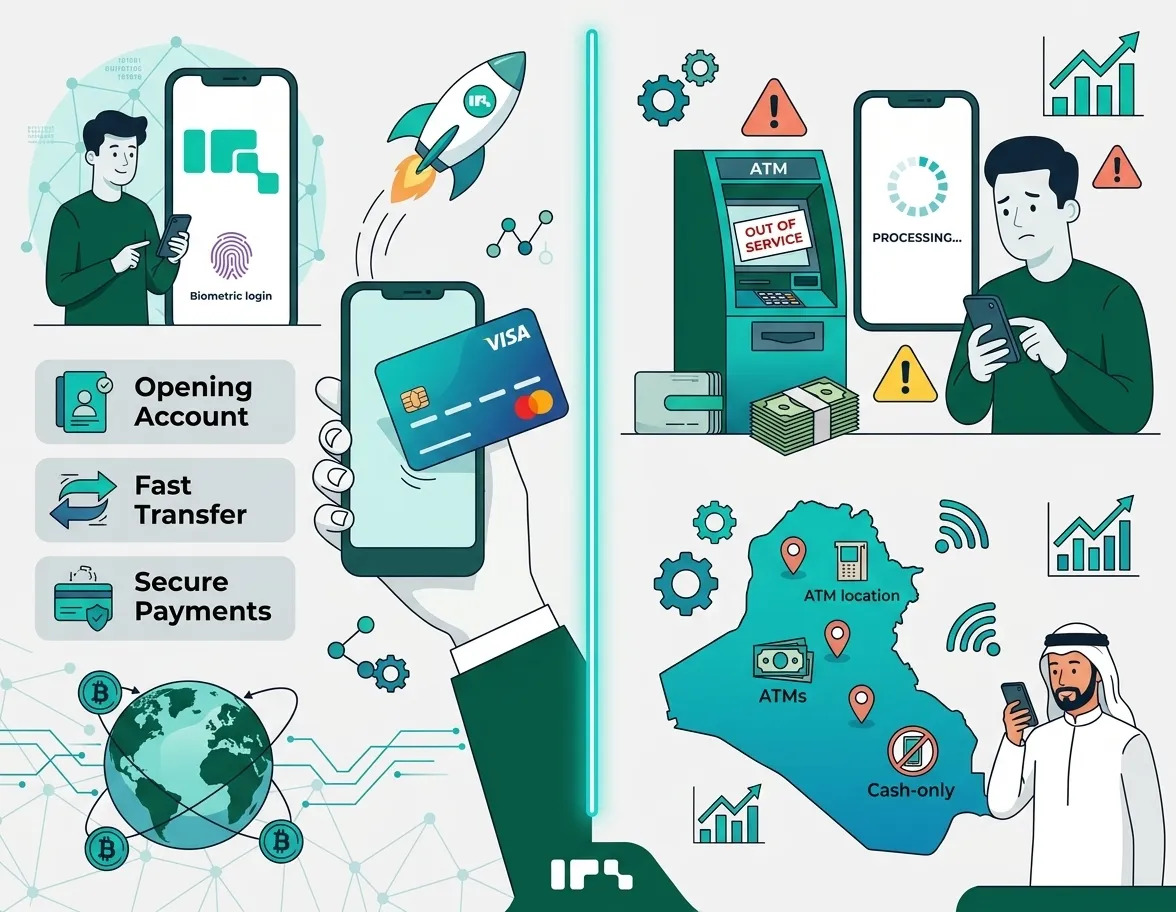
The First Iraqi Bank (FIB) app stands out as one of Iraq’s premier fully digital banking and smart financial platforms. It integrates features such as instant account opening, fund transfers, online shopping, and QR-code-based electronic payments—offering a modern experience designed to foster financial inclusion and reduce reliance on traditional cash-based transactions.
The First Iraqi Bank (FIB) app stands out as one of Iraq’s premier fully digital banking and smart financial platforms. It integrates features such as instant account opening, fund transfers, online shopping, and QR-code-based electronic payments—offering a modern experience designed to foster financial inclusion and reduce reliance on traditional cash-based transactions.
The FIB App
The application allows users to open a bank account digitally within minutes, without the need to visit a physical branch. It provides instant issuance of Visa and Mastercard cards, facilitates QR-code payments and purchases, enables rapid fund transfers, and offers flexible management of daily expenses.
Drawbacks and Challenges of the FIB App
Despite the technological revolution the app brings to the local banking sector, it faces certain operational and technical challenges. Users often encounter difficulties when depositing funds or withdrawing large amounts of cash, primarily due to a limited number of bank-affiliated ATMs and a heavy reliance on a specific network of agents—who may not always have sufficient liquidity on hand. Furthermore, users may experience delays or failures in completing fund transfers and processing payments during periods of system maintenance or high network traffic. On the other hand, some customers complain about delays in resolving outstanding financial issues and occasional slow responses from customer service. Other concerns include the application of varying commissions on foreign currency purchases, the existence of caps on daily transfers, and challenges such as the limited availability of digital point-of-sale terminals, alongside a cultural resistance—rooted in widespread public preference—toward moving away from traditional cash-based transactions.