Asiacell and AsiaPay: A Comprehensive Analysis of the Pros and Cons of Digital Payments in Iraq
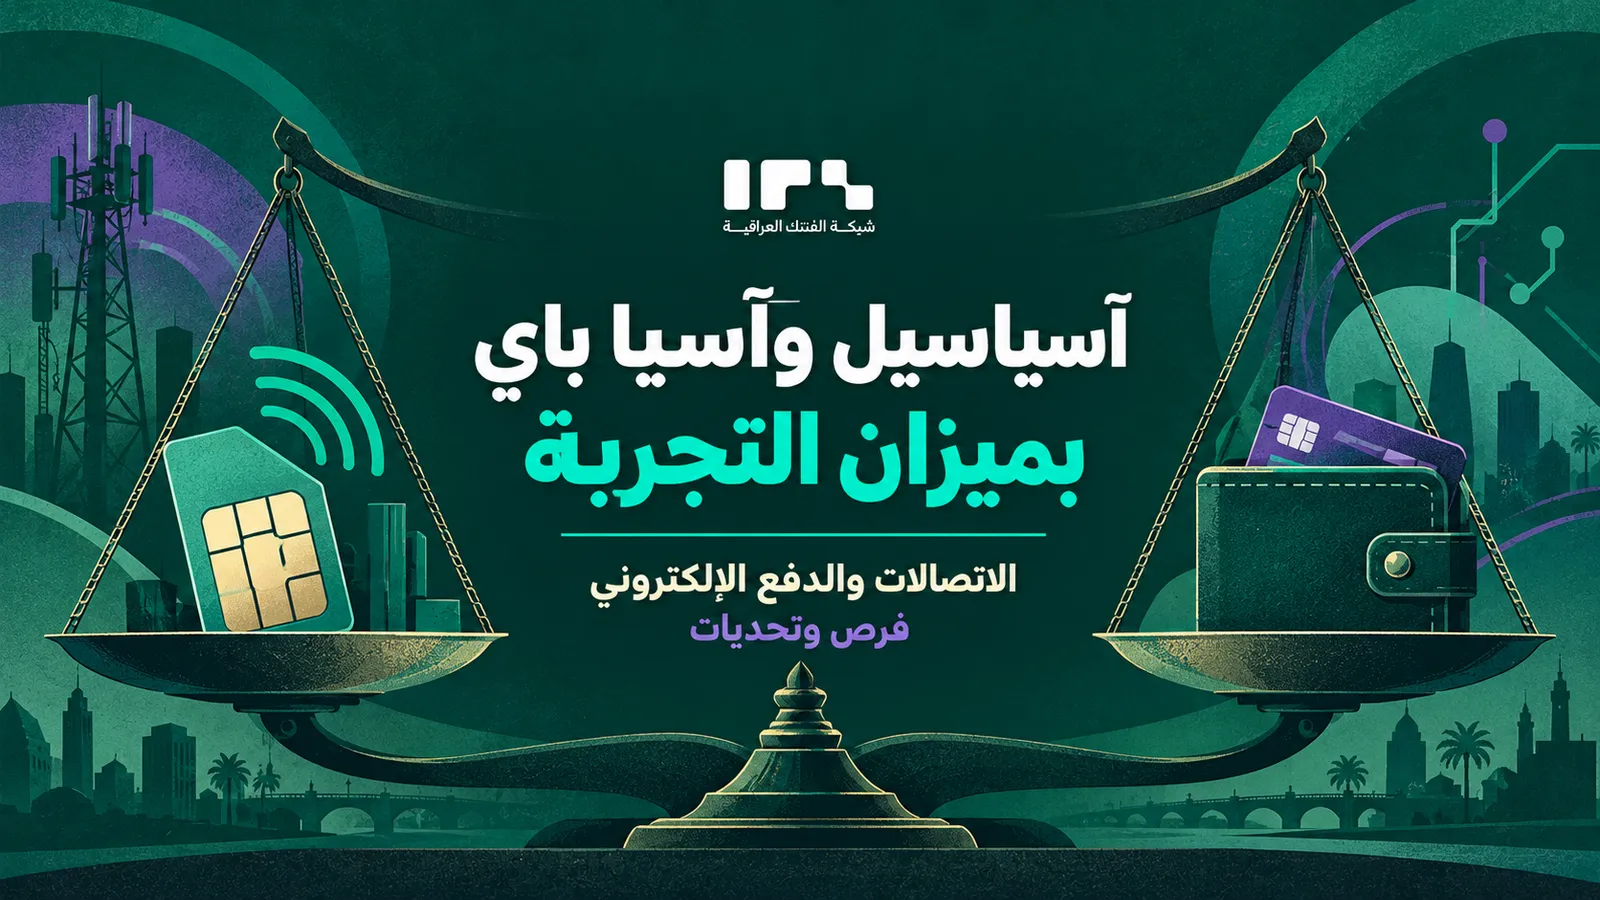
This article presents a balanced analysis of the pros and cons of Asiacell and AsiaPay in Iraq, highlighting financial inclusion and automation alongside challenges like high cash-out fees, failed transactions, and customer support bottlenecks.
Between Telecommunications and Electronic Payments: Weighing the Pros and Cons of the "Asiacell" and "AsiaPay" Model
Date: October 24, 2026
In emerging digital economies, the success of telecommunications companies is no longer measured solely by their ability to provide network coverage and voice services; rather, it is gauged by their capacity to transform their subscriber base into a stable and equitable financial transaction ecosystem.
The integration between the "Asiacell" application and the "AsiaPay" wallet—licensed by the Central Bank of Iraq—serves as a local example of the "Telco-FinTech" phenomenon. While this model offers tangible benefits that pave the way for financial inclusion, it also presents operational and structural challenges that can directly impact public trust.
First: The Advantages (Opportunities and Drivers of Digital Transformation)
Direct Access and Transactional Convenience:
Telecommunications companies possess a vast user base—a scale that most traditional banks lack. The application effectively turns a smartphone into a financial hub, allowing users to manage balances, top up subscriptions, and pay bills with the tap of a button, thereby reducing the need to visit physical retail locations or traditional top-up outlets.
Promoting Financial Inclusion and a Cashless Economy:
The "AsiaPay" wallet provides options for deposits, withdrawals, peer-to-peer wallet transfers, and the issuance of Mastercard products (both virtual and physical). These tools open doors to online shopping and digital commerce for a broad segment of the population that does not hold a traditional bank account. Process Automation and Reduction of Bureaucracy:
Direct financial transactions via electronic wallets help minimize paperwork and reduce reliance on intermediaries, thereby accelerating the execution of daily payments for both merchants and individuals.
Second: Disadvantages (Operational Obstacles and Challenges)
High Commissions and Cash-Out Fees:
Commissions charged for transferring funds or withdrawing cash through agents and outlets are relatively high compared to banking alternatives. This imposes an additional burden on low-income groups and diminishes the appeal of relying exclusively on an electronic wallet.
The Issue of Failed (Pending) Transactions:
In the event of network outages or server latency, funds may be deducted from a user’s wallet without reaching the intended recipient. This problem is compounded by slow refund processes, which disrupt the daily transactions of users.
Poor Technical Support and Ambiguous Responsibility:
When a technical glitch occurs, users often find themselves caught in a cycle between the telecommunications company’s customer service and its authorized agents. This creates a complex user experience that effectively replicates bureaucracy—albeit in a digital format.
Limited Merchant Acceptance:
Despite the proliferation of electronic wallets, most merchants and local shops still prefer cash transactions. Consequently, users are often forced to withdraw their funds as cash—incurring additional fees—rather than making direct digital payments. "Fintech is not measured by the number of icons on an app’s interface, but rather by how smoothly and quickly problems are resolved when a transaction fails and funds are held up."
Conclusion
The model combining telecommunications with electronic payments—through Asiacell and AsiaPay—represents a serious step toward reducing reliance on cash in Iraq. However, the benefits will only truly outweigh the drawbacks if the latter are addressed: by lowering commissions, accelerating the refund of held funds, and fostering a commercial ecosystem that enables the use of digital wallets for direct purchases, eliminating the need for cash.